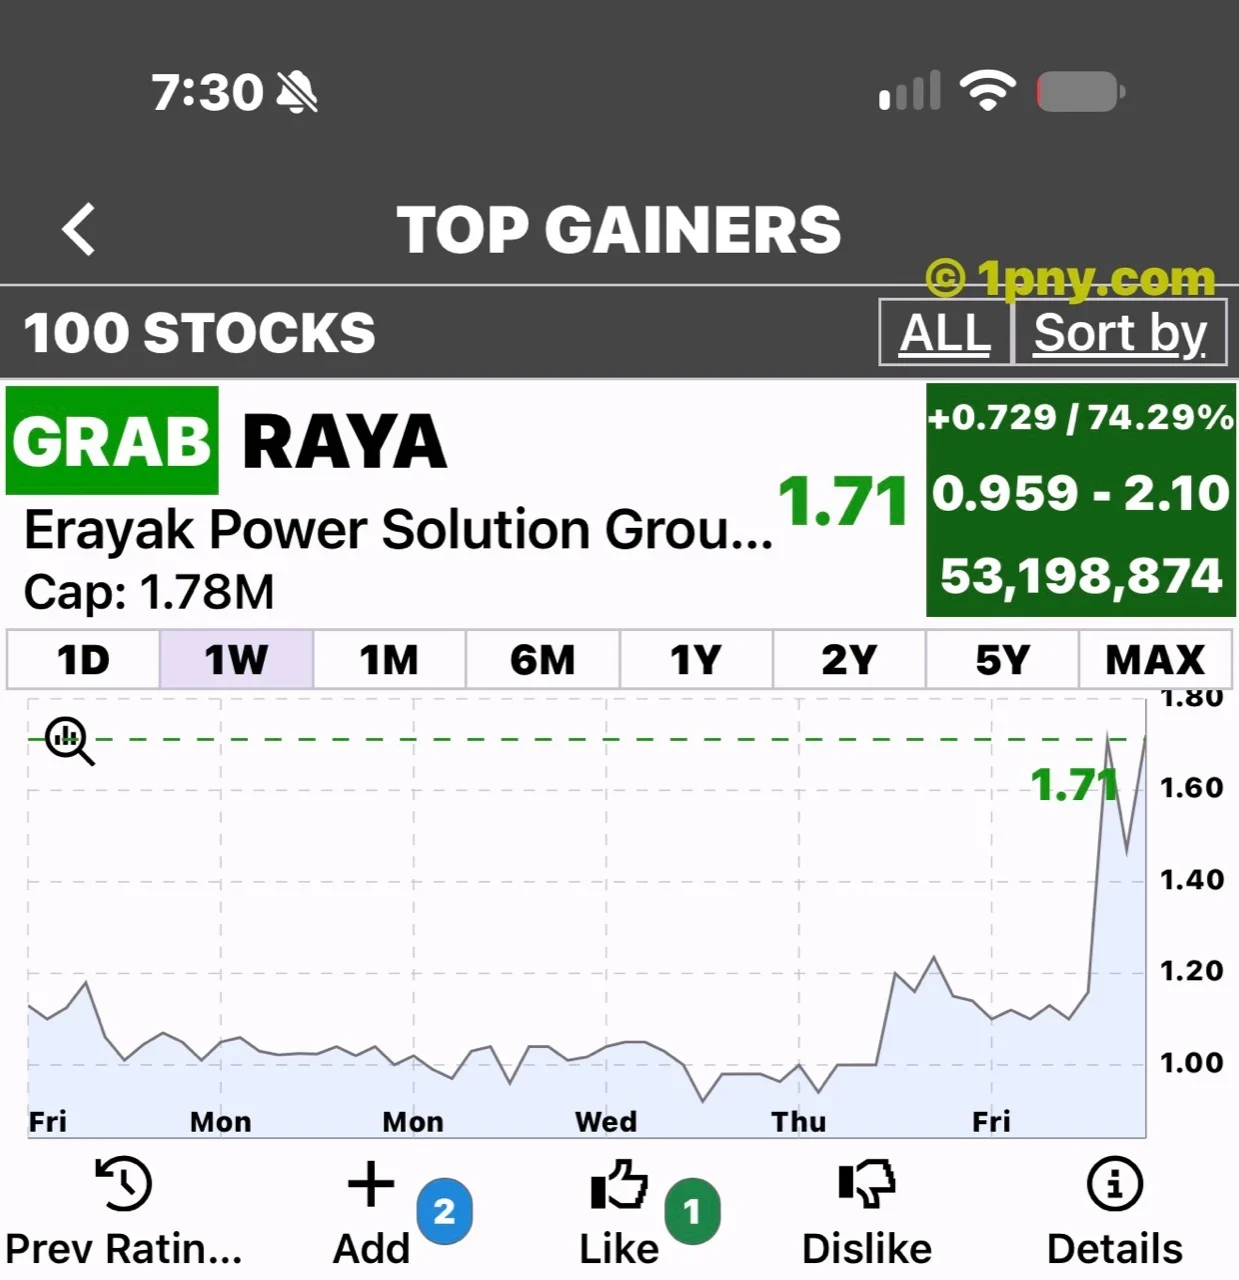
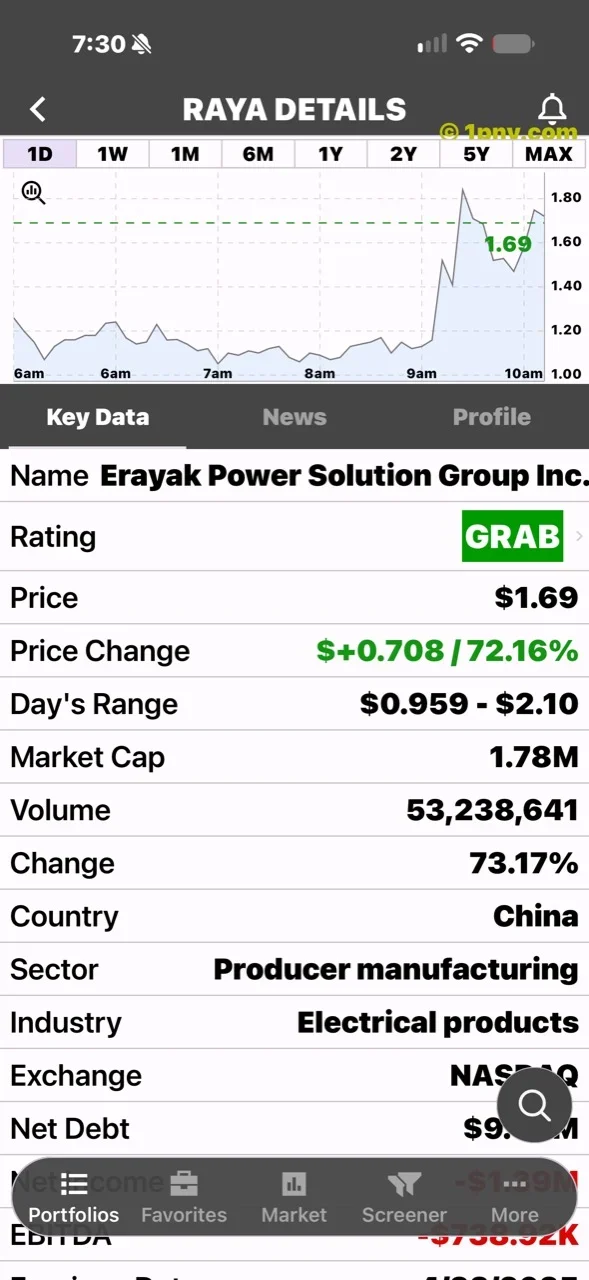
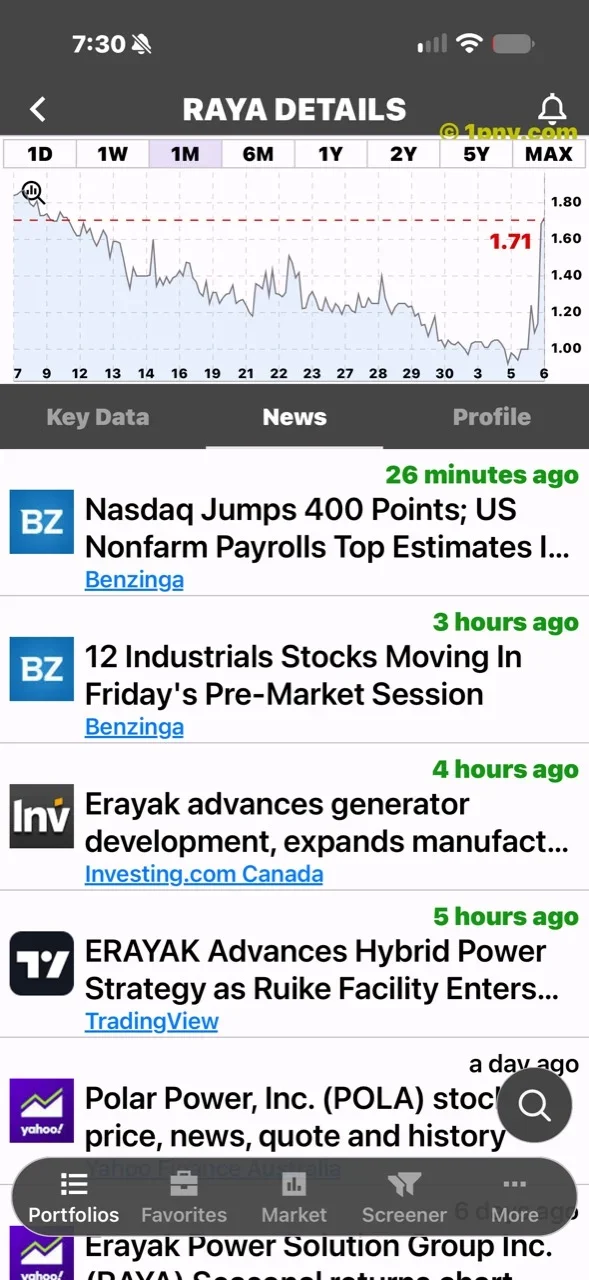
Erayak Power Solution Group's supplied PennyGems snapshot shows RAYA at $1.71, up 74.29%, following a November 6 update on its manufacturing expansion and next-generation power products. The announcement gives investors a concrete development to examine: progress toward additional production capacity and a higher-output generator platform.
The opportunity is still a development story. Factory acceptance, product validation, customer orders and profitable delivery remain separate milestones. The captured price is not a live quotation or a closing result, and the announcement does not establish the motivation behind every trade.
Factory progress gives the expansion a clearer timetable
Erayak said its Ruike facility had entered final construction acceptance, with acceptance of the main buildings expected in the first quarter of 2027. Production is planned to start in phases from late 2026 through late 2027. The energy-storage portion has planned annual design capacity of 150 MWh, rather than demonstrated output. [Company announcement](https://www.prnewswire.com/news-releases/erayak-advances-hybrid-power-strategy-as-ruike-facility-enters-final-acceptance-phase-302931939.html).
That is a meaningful operational checkpoint, but a building becoming available is only one part of commercialization. Equipment needs to work consistently, products need to meet requirements, and customers need to place orders at prices that support acceptable margins.
For investors, the useful distinction is between what a facility could eventually produce and what it is currently producing and selling. Design capacity cannot be multiplied by an assumed selling price and treated as a revenue forecast. Utilization, product mix and customer demand determine the eventual contribution.
The generator program remains ahead of commercial launch
The company also said a tri-fuel inverter generator targeting up to 16 kW was approaching pilot production. The new generator, battery-storage and hybrid programs remain under development or preparation for pilot production and are not yet commercially available. [Company announcement](https://www.prnewswire.com/news-releases/erayak-advances-hybrid-power-strategy-as-ruike-facility-enters-final-acceptance-phase-302931939.html).
Pilot production is useful because it can expose manufacturing problems before a broader launch. It is not equivalent to completed commercial deliveries. Investors should look for validated specifications, a launch timetable, production consistency and evidence of customer acceptance.
The potential attraction is a broader product range addressing portable and household backup-power needs. The financial test is whether that range creates incremental profitable sales. A compelling engineering concept can attract attention without yet establishing the cost, reliability or demand needed for a durable business improvement.
Recent growth came with weaker margins and cash use
Erayak's October financial filing reported first-half sales of $12.17 million, up 39.17%. Gross margin declined to 15.63% from 19.86%, while net loss widened to approximately $761,000 from $517,000. Operating activities used about $3.74 million of cash. [Financial filing coverage and underlying disclosures](https://www.stocktitan.net/sec-filings/RAYA/6-k-erayak-power-solution-group-inc-current-report-foreign-issuer-ab324b7195ca.html).
Those figures provide context for the expansion. More sales do not automatically create stronger earnings when costs rise faster or margins narrow. Additional capacity can support growth, but it can also require spending before the associated revenue arrives.
Cash conversion therefore deserves attention alongside the new-product timetable. Investors should evaluate whether receivables, inventory and operating spending absorb the benefits of higher sales. The prospect of a larger business is more valuable when the company can finance it on sustainable terms.
What would give the rally lasting support?
The next checkpoints are acceptance and commissioning updates, successful pilot output, commercial availability and orders that become cash receipts. Later financial results should show whether new products improve the margin profile rather than simply increase volume.
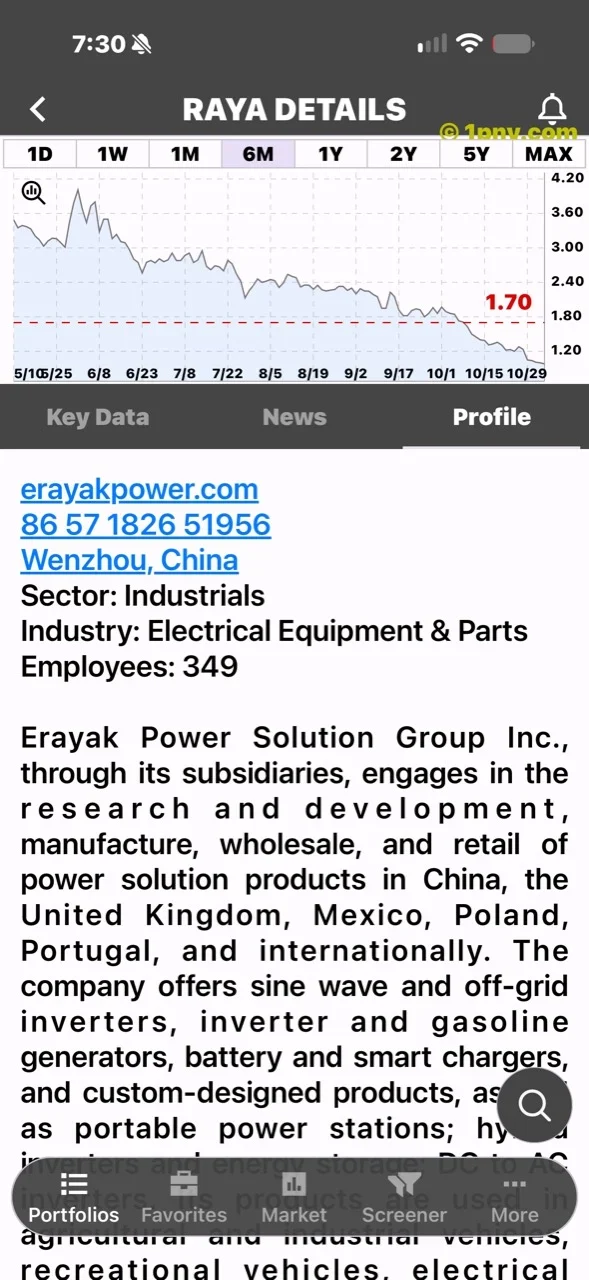
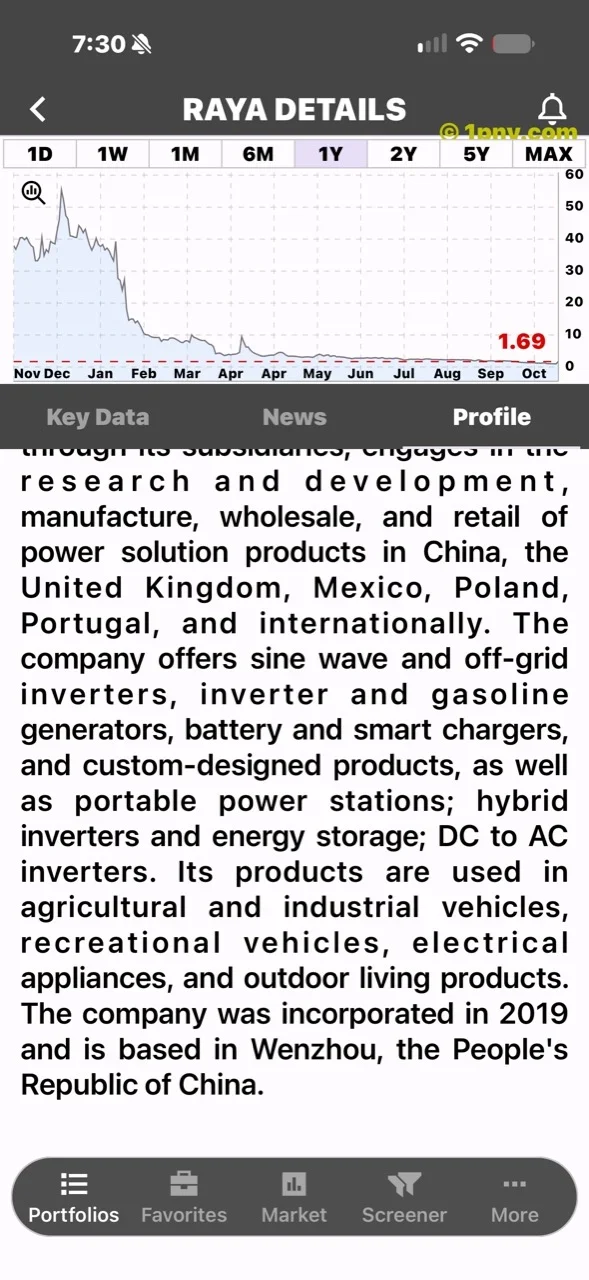
The supplied chart records a sharp rebound after a longer period of weakness. That does not by itself establish a lasting reversal. A high-volume session can reflect rapid trading in both directions; it is not proof of customer demand for generators or batteries.
The most useful recovery case links operating milestones to measurable financial results. Delays, weak margins or continuing cash consumption would challenge that case even if the development roadmap remains ambitious. The appropriate follow-up is execution evidence, not an assumption that the percentage gain must continue.
Images: PennyGems / 1pny.com. The cover shows $1.71 and a 74.29% gain; other supplied screens show slightly different captured readings. General market and unrelated company headlines in the news screen are not treated as Erayak catalysts. The app's GRAB badge is not this article's recommendation.